You may own low-cost index funds and a globally diversified mix of equities and still be more concentrated than you realize. When you look beyond the brokerage account and examine the household as a whole, one company may influence your paycheck, bonus, stock holdings, health coverage, retirement contributions, and future career prospects.
For high-achieving professionals and executives, this concentration often builds gradually. Equity awards accumulate. Household spending adjusts to total compensation. Benefits remain tied to the job. Professional relationships deepen within one industry. The result is not merely a concentrated stock position; it is a financial life that depends on a single employer and, often, a single sector.
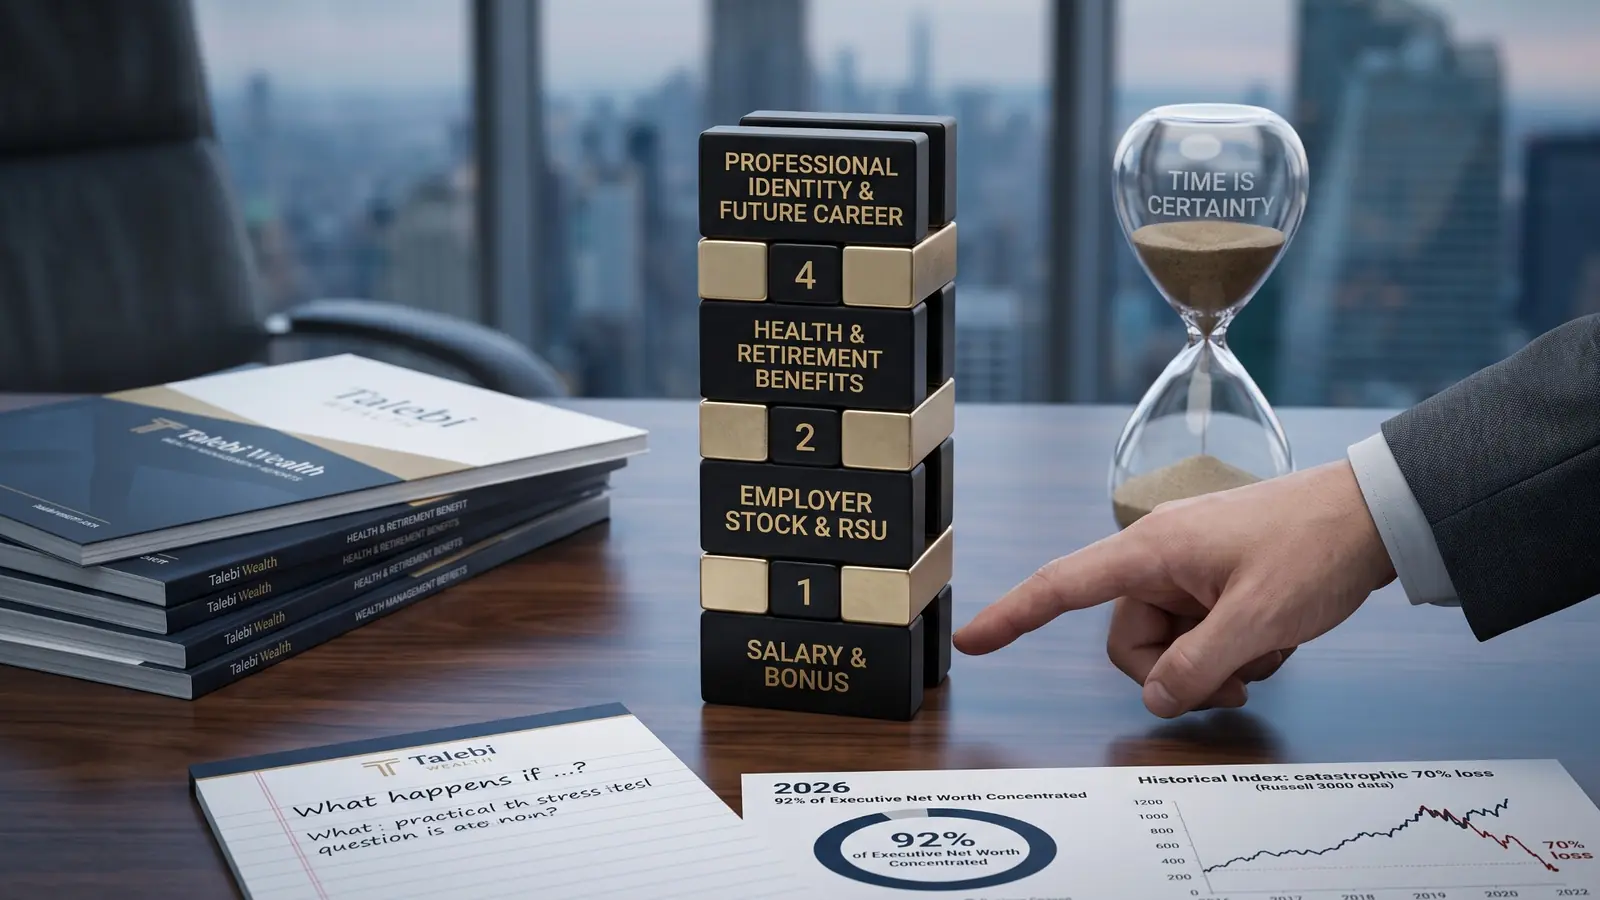
To understand the full exposure, consider four connected layers of employer concentration.
Layer 1: Salary and Bonus
Base salary is the foundation of household cash flow, but many high earners also rely on bonuses, commissions, or other variable pay. The risk is not only that a job could disappear. Variable compensation may fall well before base salary does, especially when a company or sector is under pressure.
If recurring obligations such as mortgage payments, tuition, travel, savings commitments, or lifestyle expenses assume a full year-end payout, a weaker bonus can quickly create a household cash-flow problem. A more resilient approach is to fund baseline living costs from a conservative estimate of recurring income and treat variable compensation as money for taxes, long-term saving, debt reduction, and truly discretionary goals.
Layer 2: Employer Stock and Unvested Compensation
Employer equity can magnify the same risk. At the top of public companies, stock awards can be the largest component of pay. Equilar's 2026 study of S&P 500 CEOs reported median stock awards of $10.9 million, compared with median total compensation of $17.7 million. The exact mix is different for other professionals, but the planning problem is similar: current wealth and future compensation can depend on the same company that provides the paycheck.
It is important to distinguish among vested shares you own, unvested awards that remain contingent on employment and plan terms, and diversified assets that do not depend on the employer. Combining them into one net-worth figure can hide how much is actually liquid, available, and independent of the company.
Selling employer stock can be emotionally and financially difficult. Familiarity, loyalty, optimism, taxes, blackout windows, and fear of missing future gains all encourage inaction. Yet the downside of a single company can be severe. In an analysis of companies that appeared in the Russell 3000 from 1980 through 2020, J.P. Morgan Asset Management found that more than 40% experienced a decline of at least 70% from a prior peak that was not recovered during the study period. Broad indexes can recover even when many individual companies do not, because a relatively small group of winners drives much of the index's return.
Taxes matter, but they are only one part of the decision. Holding solely to avoid capital-gains tax can allow a known tax cost to dominate a potentially much larger investment risk. A better question is: What after-tax risk is my family accepting by continuing to hold this much of one company?
Layer 3: Health, Disability, Retirement, and Other Benefits
Your employer provides more than cash and equity. It may subsidize health insurance, provide group life and disability coverage, make retirement-plan contributions, and offer other benefits that would be costly to replace independently.
A job loss does not necessarily mean every benefit disappears immediately. COBRA or Marketplace coverage may be available, and some insurance benefits may be portable or convertible. But the employer subsidy may end, premiums may rise, coverage may change, and decisions may be time-sensitive. Future retirement-plan matching also stops, and unvested employer contributions may be forfeited under the plan's vesting rules.
The vulnerability is therefore not simply 'losing insurance.' It is having to rebuild parts of the household safety net while income is disrupted and the employer's stock may also be under pressure.
Layer 4: Professional Identity and Future Career Opportunities
The final layer is human capital: your ability to earn in the future. Your experience, professional network, reputation, and career trajectory may be closely connected to your employer's industry.
When a problem is company-specific, moving to a competitor may be relatively straightforward. When the shock affects an entire sector, however, the risk compounds: the stock may fall, the job may become less secure, bonuses may shrink, and competing firms may slow hiring at the same time. A strong resume does not eliminate sector concentration.
Career diversification does not mean abandoning your expertise. It means maintaining relationships beyond one employer, developing skills that transfer across industries, understanding the external market for your role, and avoiding a professional network that exists only inside your current organization.
A high net worth can offer less protection than it appears when much of it is unvested, tax-deferred, concentrated, or difficult to access. Home equity may require borrowing or a sale. Retirement accounts may create tax costs or restrictions. Unvested equity may be forfeited or treated differently under plan-specific termination rules. The total on a balance sheet matters, but so do the location, liquidity, and independence of the assets behind it.
A Diversified Financial Life
Untangling the one-company problem rarely requires an abrupt, all-or-nothing decision. It usually requires coordination: defining a target range for employer-stock exposure, creating a tax-aware diversification schedule, building liquidity outside the employer, reviewing benefit portability, and strengthening your professional network before a job is at risk.
Diversifying employer stock is not a judgment about the company. Building independent insurance is not a prediction of job loss. Expanding your network is not disloyal. These are decisions about how much of your family's future should depend on a single outcome.
The first step is not necessarily to sell everything. It is to map the dependencies, quantify the tradeoffs, and build a sequence of decisions before urgency removes your options.
The best time to reduce one-company risk is while income is stable, choices are broad, and you are not being forced to act by a layoff, an earnings disappointment, or a falling share price.
Sources and Notes
- Equilar, 2026 Equilar | Associated Press CEO Pay Study (May 27, 2026).
- J.P. Morgan Asset Management, Case Study: Tax-Smart Transition of a Concentrated Stock Position (Russell 3000 analysis, 1980-2020).
- FINRA, Love Your Company Stock? Here's What to Know (August 11, 2023).
- Benefits continuation and vesting: U.S. Department of Labor, COBRA Continuation Coverage; HealthCare.gov, If You Lose Job-Based Coverage; and IRS, Retirement Topics - Vesting.