The raise arrived. The portfolio balance grew. Your year looked successful on paper.
Then the car needed work, a family expense appeared, and an uncomfortable thought surfaced: Why does a good financial year still feel so tight?
A year-end review can answer that question—but only if you look beyond your salary and the balance at the top of your investment statement. More income creates an opportunity. The review reveals what you did with it.
The useful year-end question is: What did this year’s income make possible that was not possible a year ago?
As 2026 draws to a close, five questions can help you turn a busy year into a clearer plan for 2027. Start with actual year-to-date figures, label any November–December estimates, and reconcile the full year when the final statements arrive.
1. Where did the raise go?
A salary increase announces itself. The spending that follows often arrives quietly: a larger car payment, more travel, additional family support, a few subscriptions, or a housing decision that seemed manageable at the time.
Some of those changes may be exactly what you wanted. The problem is losing track of the trade-off.
The latest national figures offer useful context. In September 2026, disposable personal income rose 0.2% from the previous month, while consumer spending rose 0.5%. The personal saving rate was 3.8%, according to the Bureau of Economic Analysis. That is an aggregate measure of saving relative to disposable income—not the median household’s rate or a target for your family. [1]
Inflation also matters. Consumer prices were 3.7% higher in September than a year earlier. A hypothetical $100,000 spending basket that rose at that rate would cost $103,700. Your own expenses may have changed very differently. [2]
Review your pay statements and transactions together. Compare gross compensation, taxes and payroll deductions, spendable income, and the dollars directed toward your goals. Separate higher prices from new purchases and larger commitments.
Ask yourself: If my income increased this year, how much of the increase became lasting progress—and how much became spending I now need to sustain?
2. Did your habits build wealth, or did the market do the heavy lifting?
Investment gains are real progress. They are also different from saving more, reducing debt, or improving the way you manage money. Separating those sources makes your next decision clearer.
Consider a fictional professional household reviewing its year-end projection:
| Measure | 2025 | 2026 projection |
|---|---|---|
| Annual gross household income | $240,000 | $260,000 |
| Year-end net worth | $700,000 | $790,000 |
| Annual investment contributions* | $24,000 | $18,000 |
| Year-end available cash reserves | $36,000 | $30,000 |
| Monthly essential spending at year-end | $8,000 | $9,000 |
| Cash reserve coverage | 4.5 months | 3.3 months |
Hypothetical illustration, not client results or a market forecast. Balance-sheet figures are at December 31; income and contributions cover each calendar year. The 2026 figures are estimates. *Contributions include employee and employer amounts, with no investment withdrawals. Cash reserves are uncommitted and readily available. Coverage assumes no incoming income and unchanged essential spending, including replacement benefits.
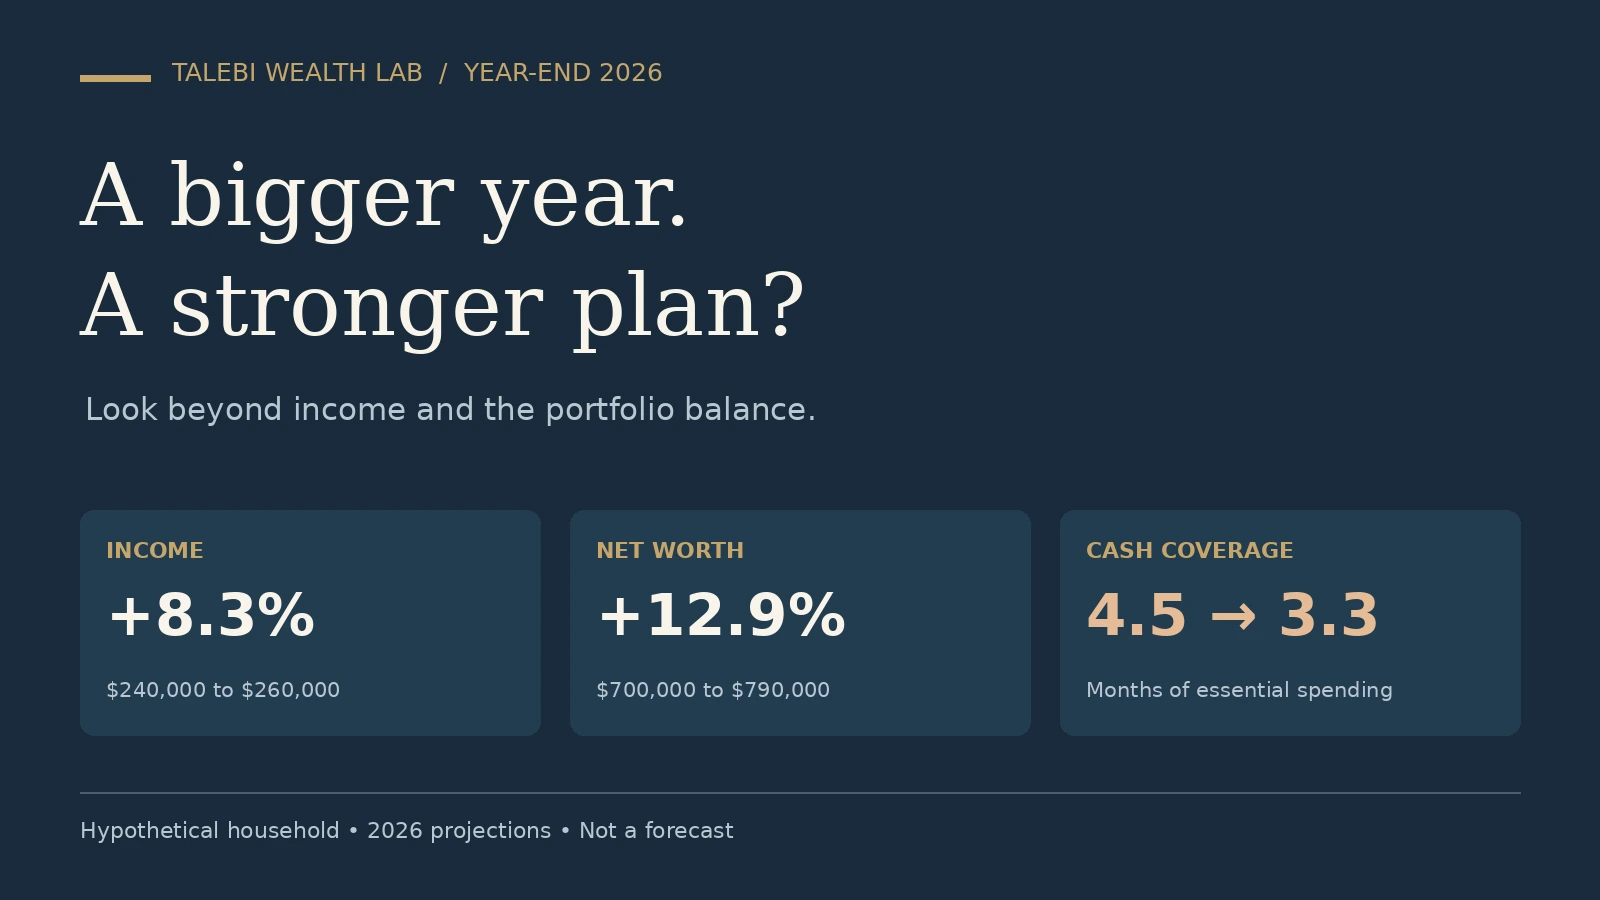
Income increased 8.3%, and net worth increased 12.9%. Yet investment contributions fell by one-quarter, while reserve coverage declined by about 1.2 months.
Here is the projected $90,000 increase in net worth:
| Source of change | Effect on net worth |
|---|---|
| New investment contributions | +$18,000 |
| Decline in cash reserves | −$6,000 |
| Mortgage principal repaid | +$12,000 |
| Investment gains, net of fees | +$66,000 |
| Total increase | +$90,000 |
The example assumes investments rise from $500,000 to $584,000, cash falls from $36,000 to $30,000, a home remains valued at $600,000, and its mortgage falls from $436,000 to $424,000. No other assets, liabilities, gifts, or transfers are assumed. Investment gains are illustrative and are not a stated return forecast.
About 73% of the increase came from investment gains. The remaining $24,000 came from the combined effect of contributions, cash use, and principal repayment.
That does not make the year a failure. It identifies the next conversation: were lower saving and higher spending deliberate, temporary choices—or did they happen without a decision?
When reviewing your own accounts, exclude transfers between accounts from new saving. Separate investment gains from deposits, and mortgage principal from interest. Keep valuation changes and one-time gifts visible. Otherwise, the same dollar can appear to have done more work than it actually did.
3. Did you gain breathing room?
A larger balance sheet is useful. So is being able to handle a surprise without disrupting it.
The Federal Reserve’s latest annual household survey, published in May 2026 and covering 2025, found that 55% of adults had set aside enough emergency savings for three months of expenses. This describes adults broadly; it does not tell us how high earners or educated professionals are doing. [3]
Meanwhile, the New York Fed reported $1.263 trillion in credit-card balances at the end of the second quarter of 2026, up $21 billion from the previous quarter. Those balances include accounts paid in full; the total is not a measure solely of interest-bearing debt. [4]
For your review, calculate available reserves divided by essential monthly expenses. Exclude money already committed to taxes, tuition, or a planned purchase. Then ask what would happen if income stopped, an employer benefit disappeared, or a major bill arrived.
Review debt balances and interest rates, insurance needs, beneficiaries, and exposure to one employer. If your paycheck, company stock, and benefits all depend on the same organization, several risks could materialize together.
Ask yourself: What disruption could I manage today that would have forced me to borrow or sell investments a year ago?
4. Which decisions have a December deadline?
A year-end review becomes valuable when it leaves enough time to act. Start with the decisions whose timing is difficult to reverse.
Check retirement contributions against the right limit
| Account / eligibility | 2026 limit |
|---|---|
| 401(k) or 403(b): regular employee elective deferral | $24,500 |
| With standard age-50+ catch-up, if permitted* | $32,500 total |
| With higher catch-up for ages 60–63, if permitted* | $35,750 total |
| Traditional and Roth IRAs combined: under age 50 | $7,500 |
| Traditional and Roth IRAs combined: age 50+ | $8,600 |
Selected limits, not a complete contribution guide. *Age is determined at year-end. The age-60–63 catch-up replaces the standard age-50+ catch-up; they are not added together. Workplace figures exclude employer contributions and other special provisions. IRA limits are also constrained by eligible compensation; Roth eligibility and traditional IRA deductibility depend on income and other conditions. [5]
For calendar-year workplace deferrals, contact payroll now about the remaining pay dates, contribution elections, and employer-match rules. Waiting until the last week of December may leave too little eligible pay to make the change.
There is an additional 2026 detail for some higher earners: catch-up contributions generally must be Roth if prior-year wages from the sponsoring employer exceeded $150,000. Confirm how your plan applies the rule. [6]
IRA contributions follow a different timetable: they generally can be made through the tax-return filing deadline, excluding extensions. Do not confuse that window with the timing for workplace salary deferrals. [7]
Review the tax picture before choosing a transaction
Bring your expected income, withholding, realized investment gains and losses, and planned gifts into one discussion. A bonus, stock compensation, or consulting income can change the result.
- Investment losses: Review whether realizing a loss in a taxable account fits your investment plan. Wash-sale rules can disallow the deduction when substantially identical securities are purchased within 30 days before or after the sale. Coordinate across accounts, including IRAs and a spouse’s purchases. [8]
- Charitable giving: The 2026 rules deserve a fresh look. Itemizers generally face a new floor equal to 0.5% of adjusted gross income. At $300,000 of AGI, that floor is $1,500; a $5,000 otherwise eligible gift would leave $3,500 before other applicable limits. Eligible non-itemizers may instead deduct up to $1,000 of qualifying cash gifts, or $2,000 if married filing jointly. Complete intended 2026 gifts within the year and allow processing time. [9] [10]
- Roth conversions: If one is appropriate, coordinate the 2026 transaction with the custodian well before its year-end cutoff. Untaxed amounts converted generally add taxable income, and a completed conversion cannot be undone through recharacterization. Model the tax consequences first. [11] [12]
The right outcome may be a transaction—or a documented decision to leave things alone. A deadline creates a need to review, not an obligation to act.
5. What will you change before the first paycheck of 2027?
“Save more next year” is a wish. “Move $500 from each twice-monthly paycheck into our reserve account starting in January” is an instruction. Over a full year, that would direct $12,000 toward the goal, before interest.
Choose three changes you can actually sustain. Give each a dollar amount or clear completion standard, a responsible person, and a date. For example:
- Build the reserve: Automate $500 twice monthly; review progress March 31.
- Direct the next raise: Calculate the after-tax increase and assign an agreed share to goals before expanding recurring spending.
- Close one planning gap: By January 31, complete the insurance, beneficiary, or employer-stock review you identified.
Those are illustrations, not universal targets. The useful commitment is the one that addresses your actual gap and fits your cash flow.
A year can include lower saving for good reasons: a new child, caregiving, education, a career transition, or time you deliberately chose to enjoy. The review helps you see what those choices cost and what needs to happen next.
Before you close the books on 2026, look at what your money accomplished. Then give the next year’s income a clearer assignment.
A raise is worth celebrating. So is knowing exactly how it is improving your life.
Sources and methodology
Reviewed November 7, 2026. Monthly and quarterly statistics describe the latest releases verified as of that date; they are not full-year 2026 results. National figures describe broad populations and do not estimate outcomes for high earners. All household examples, projections, calculations, and planning interpretations are illustrative editorial analysis.
- BEA: Personal Income and Outlays, September 2026, October 29, 2026. Estimates may be revised.
- BLS: September 2026 Consumer Price Index, October 14, 2026. CPI-U, 12-month change, not seasonally adjusted.
- Federal Reserve: Economic Well-Being of U.S. Households in 2025, Savings and Investments, May 2026.
- New York Fed: Q2 2026 Household Debt and Credit, August 11, 2026. Q3 release is scheduled for November 10, after this review date.
- IRS: 2026 retirement contribution limits, November 13, 2025; applies to tax year 2026.
- IRS Notice 2025-67, Internal Revenue Bulletin 2025-49, including the wage threshold governing 2026 Roth catch-up contributions.
- IRS Publication 590-A: IRA contribution timing. General timing rule; use the separately cited 2026 limits.
- IRS Publication 550: Investment Income and Expenses, wash sales.
- IRS Publication 505 (2026), new charitable deductions and itemizer floor.
- 26 U.S.C. §170(a)(1), payment within the taxable year.
- IRS: IRA FAQs, taxation of Roth conversions and prohibition on conversion recharacterization.
- Fidelity: Roth conversion checklist, example of a custodian’s December 31 submission cutoff. Other custodians may impose different operational deadlines.