A surgeon earning $550,000 a year and a schoolteacher earning $65,000 a year can retire with the same net worth.
I have watched this happen more than once. It never comes down to intelligence, and it rarely comes down to income. It comes down to a single, critical distinction: whether income ever became capital.
This distinction isn't a motivational line; it is showing up in national data right now among the exact population most people assume has finance completely figured out.
Consider the current landscape:
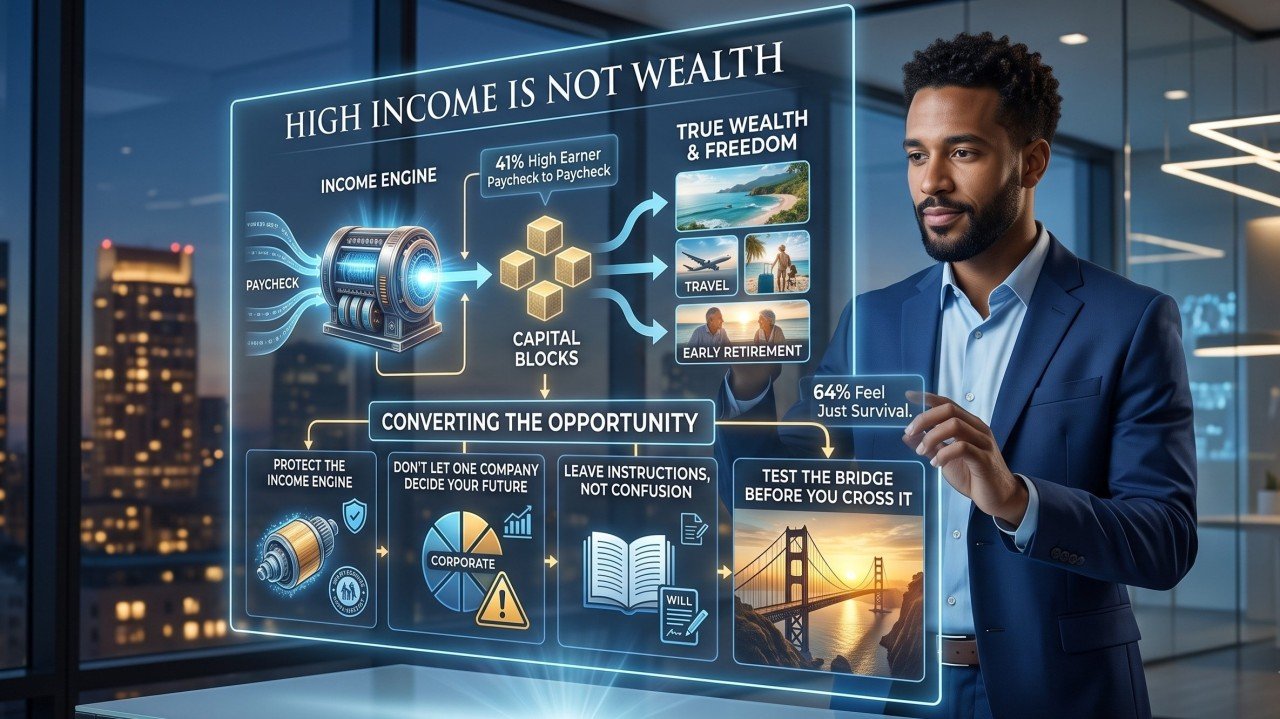
- The Paycheck Trap: A recent Goldman Sachs survey found that 41% of households earning $300,000 to $500,000 a year say they are living paycheck to paycheck - a higher share than households earning $50,000 to $100,000.
- The Wealth Illusion: The Harris Poll’s Income Paradox Survey revealed that 64% of six-figure earners feel their income is less like wealth and more like a basic way to survive.
- The Credit Leverage: Nearly half of adults earning over $200,000 report leaning on credit cards just to get through the month.
None of this is a story about irresponsibility. Physicians, engineers, attorneys, professors, and executives are, on average, some of the most disciplined and analytical people in the workforce. The problem is that financial planning is an entirely different discipline than the one that earned the income in the first place, and almost no elite career teaches it along the way.
High income gives you opportunity. Wealth gives you freedom. A comprehensive financial plan is what turns one into the other, deliberately, instead of by accident.
Four Vulnerabilities in a High-Earners Financial Picture
When analyzing the financial structures of highly educated professionals, four specific areas tend to matter most:
1. Protect the Engine, Not Just the Paycheck
Picture your income as the engine running your entire financial life, your mortgage, your children's education, your retirement savings, and your lifestyle. Every single piece of your plan depends on that engine staying on.
Yet, while most high earners rush to insure their homes, cars, and luxury assets, they frequently overlook the asset generating all of it: their own ability to work. Social Security Administration actuarial tables show that just over one in four of today’s 20-year-olds will experience a disability before reaching retirement age. Despite this, an analysis by the American Council of Life Insurers found that 53.7% of non-retired U.S. households, more than 51 million families, have no disability insurance beyond state and federal minimums.
Disability insurance isn't a product born out of fear. It is simply a protective casing for the engine that powers everything else.
2. Don't Let One Company Decide Your Future
This vulnerability shows up constantly with tech engineers, corporate executives, and physicians tied to a single practice or employer. Equity compensation, RSUs, ESPPs, or decades of loyalty can quietly build a position where one company represents 30%, 40%, or even 60% of an individual's net worth.
Standard industry guardrails dictate that once a single holding passes roughly 20% of your net worth, company-specific risk becomes a major driver of your entire financial picture. No amount of diversification elsewhere can offset it. Diversifying out of a concentrated position is not a vote of no confidence in your company; it is a way of making sure one bad quarter or product recall cannot take your entire family plan down with it.
3. Leave Instructions, Not Confusion
Statistically, estate planning is the area highly educated professionals are most likely to skip—not due to a lack of assets, but because it rarely feels urgent.
Trust & Will’s 2026 Estate Planning Report found that 56% of U.S. adults completely lack the five core estate documents: a will, a trust, a medical power of attorney, a financial power of attorney, or a HIPAA authorization. Furthermore, Caring.com’s historical data shows the share of Americans with a valid will has actively fallen from 33% down to just 24%.
Estate planning was never truly about the size of the balance sheet. It is about whether the people you love have a clear instruction manual or a guessing game at the exact moment they can least afford one.
4. Test the Bridge Before You Cross It
Retirement confidence has posted its sharpest drop in years. EBRI’s 2026 Retirement Confidence Survey found that only 61% of American workers feel confident they will have enough money to live comfortably in retirement, down from 67% and marking the lowest reading since 2017.
This pressure is particularly visible among high-burnout fields. American Medical Association data shows physician burnout sitting at 41.9%, with roughly one in four doctors considering leaving clinical medicine entirely. Many desire to scale back hours long before a basic spreadsheet says it is "allowed."
A real financial plan doesn't wait until the day you want to walk across that retirement bridge to find out if it holds. It stress-tests the structure years in advance - simulating income, spending, healthcare, taxes, and sequence-of-returns risk - while you still have the time and income to reinforce it.
Why a Plan, Not Just a Portfolio, Moves the Needle
The clearest evidence for structured planning comes from looking at what successful individuals do differently. Northwestern Mutual’s 2026 Planning & Progress Study found that 74% of American millionaires work with a financial advisor - more than double the rate of the general population. These advisor-guided households also expect to retire about 2.5 years earlier on average and feel far more prepared for the transition (74% vs. 43%).
This performance gap doesn't exist because professionals have access to "secret" or exclusive investments. Advisors and investors look at the exact same mutual funds, the same tax codes, and the same insurance markets.
The actual return on planning comes from coordination. It is the practice of ensuring your investments, insurance, corporate stock options, tax strategies, and estate documents play together like sections of a synchronized orchestra, rather than five separate decisions made under pressure at five separate times.
Traditional Approach vs. Comprehensive Planning
The Takeaway
Being excellent at medicine, engineering, law, academic research, or corporate leadership does not automatically make anyone excellent at personal finance, and it was never supposed to. Wealth management is a separate, distinct discipline. The good news? It rewards the exact same evidence-based, structured thinking you already apply daily in your own career.
Financial planning can feel overly complex, but good advice should always be inherently understandable. True wealth management is about turning complex planning issues into clear, memorable, and actionable steps.
If any of the metrics or gaps outlined above made you pause, that pause is worth a real strategic conversation, not just a look at another spreadsheet. Let’s connect to build a clear path from your income to your freedom.