Practical Takeaways for Educated Professionals
I recently read Factfulness: Ten Reasons We’re Wrong About the World -- and Why Things Are Better Than You Think by Hans Rosling, with Ola Rosling and Anna Rosling Rönnlund. I found it very useful not only for understanding the world more accurately, but also for improving how we make financial decisions.
At first glance, Factfulness is not a personal finance book. It is not about budgeting, investing, taxes, retirement accounts, or insurance. But it is highly relevant to financial planning because it teaches a powerful lesson:
We often make decisions based on distorted perceptions of reality.
Rosling explains that many people, including highly educated people, misunderstand the world. They often believe the world is poorer, more dangerous, less healthy, and less developed than it really is. The book does not say the world has no problems. It says we often misunderstand the scale, direction, and distribution of those problems. One of the most important lessons is:
Bad things can be true, while the world can still be improving.
Financial decisions are often made under uncertainty, fear, incomplete information, and emotional pressure. Educated professionals may understand investments, taxes, markets, and economics, but they are still human. They still react to headlines, political narratives, market volatility, social comparison, and recent events. In financial planning, people rarely bring only numbers. They bring stories:
“I feel like the economy is collapsing.”
“The market is too risky.”
“I don’t think retirement is possible anymore.”
“Taxes will ruin everything.”
“Health care costs will make retirement impossible.”
“I saw something on the news, and now I want to change my portfolio.”
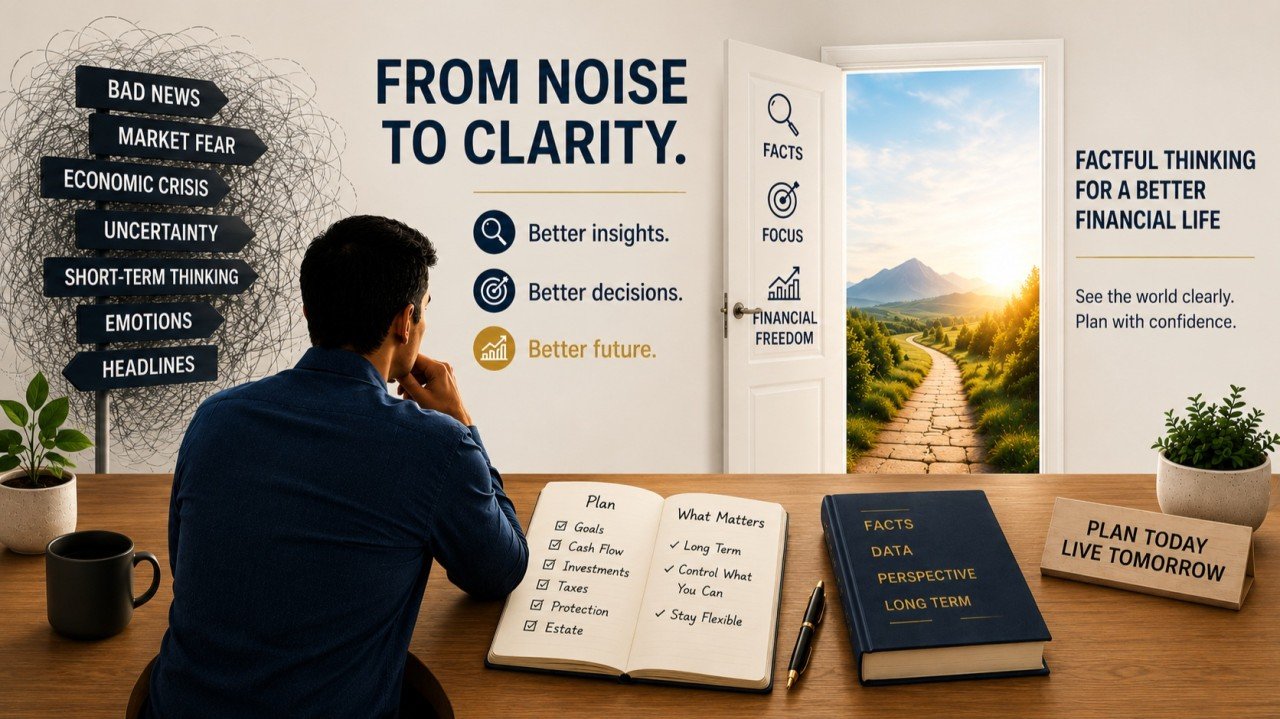
Some of these concerns contain truth. But many are exaggerated by human instincts. Factfulness helps us separate real risk from exaggerated fear, long-term trends from short-term noise, data from drama, planning from panic, and useful caution from emotional pessimism. For me, the major takeaway is this:
A strong financial planner does not simply provide projections. A strong financial planner helps clients interpret reality more accurately.
Why Factfulness Matters for Financial Planning
Personal finance is not only about knowing what to do. It is about making good decisions when the future is uncertain.
Should I invest now? Should I retire? Should I hold more cash? Should I buy a house? Should I sell my investments? Should I change my portfolio because of the election? Should I pay down debt? Should I buy insurance?
These decisions involve numbers, but they also involve judgment. And judgment can be distorted. The book teaches us to ask:
Am I seeing the full picture?
Am I reacting to fear?
Am I using the right comparison?
Am I assuming the future will look exactly like the present?
Am I confusing a headline with a planning problem?
Am I making this decision with data, or with emotion?
The ten instincts in Factfulness show why smart people often misread reality. The same instincts that cause people to misunderstand global trends can also cause them to misunderstand their own financial lives. Here is the list of ten instincts:
1. The Gap Instinct: Avoid All-or-Nothing Financial Thinking
The gap instinct is the tendency to divide things into two extremes: rich versus poor, safe versus risky, successful versus failing, on track versus completely behind. In financial planning, educated professionals often think in false binaries:
“I am either financially successful or failing.”
“I am either on track or completely behind.”
“The market is either safe or dangerous.”
“Debt is either good or bad.”
“Real estate is good, stocks are bad.”
But financial reality is usually more complex. A client may not be perfectly on track, but that does not mean they are in crisis. A portfolio may have risk, but that does not mean it is reckless. Debt may be harmful in one context and useful in another. A retirement plan may need adjustment, not abandonment. A better framework uses levels instead of extremes:
- Strong position
- Manageable with minor changes
- At risk without adjustment
- Serious concern requiring immediate action
Instead of asking, “Am I succeeding or failing?” ask:
What is my current position, and what adjustment would improve it?
2. The Negativity Instinct: Do Not Let Bad News Control the Plan
The negativity instinct is the tendency to notice bad news more than good news. This is everywhere in finance. People hear about inflation, recessions, wars, political conflict, layoffs, market declines, tax uncertainty, and debt crises. These stories feel urgent. Meanwhile, progress is often quiet. Innovation, productivity, long-term market recovery, stronger financial tools, and personal financial progress usually receive less attention.
Bad news is loud. Progress is quiet.
This can cause people to sell investments during downturns, delay investing, hold too much cash, avoid retirement, or underestimate their own progress. The lesson is not to ignore bad news. The lesson is to ask:
Is this bad news, or is this a broken plan?
A market decline may be bad news. But if the client has diversification, cash reserves, a long-time horizon, and no immediate need to sell, the plan may still be intact. A useful framework:
What is bad right now?
What is improving over time?
What action does the plan actually require?
Not every negative headline requires a financial action.
3. The Straight-Line Instinct: The Future Will Not Move in a Straight Line
The straight-line instinct is the assumption that current trends will continue forever. In personal finance, people often project the present into the future:
“My income has been rising, so it will keep rising.”
“The market has been falling, so it will keep falling.”
“My expenses are manageable now, so they will stay manageable.”
“My business is growing, so I can take on more debt.”
But financial life rarely moves smoothly. Income changes. Expenses spike. Markets cycle. Careers shift. Families evolve. Tax rules change. Health changes. Retirement spending changes. That is why good planning uses scenarios, not single-line projections. For major plans, consider:
- Base case
- Stress case
- Opportunity case
For retirement planning, test lower returns, higher inflation, earlier retirement, health care costs, long-term care, one spouse living longer, higher taxes, and a major market decline early in retirement. The goal is not to predict one exact future. The goal is to build a plan that can adapt to multiple possible futures.
4. The Fear Instinct: Measure Risk Before Reacting to It
The fear instinct causes people to pay too much attention to vivid, frightening risks. In finance, people may fear market volatility more than inflation, temporary losses more than permanent loss of purchasing power, investing more than failing to invest, insurance premiums more than catastrophic uninsured events, or estate planning conversations more than family confusion later. Fear is not always irrational. But fear needs measurement.
When a client says, “I am worried,” the next step is not to dismiss the concern. The next step is to define it. Ask:
What exactly are we worried about?
How likely is it?
What would the financial impact be?
What protection already exists?
What would reduce the risk to an acceptable level?
What risk are we ignoring because this fear is taking all the attention?
Good planning does not eliminate fear. It organizes fear.
Fear says, “Do something now.”
Planning asks, “What is the risk, and what action actually improves the situation?”
5. The Size Instinct: Numbers Need Context
The size instinct is the tendency to misjudge a number when we see it alone. This is extremely relevant to personal finance. People react emotionally to isolated numbers:
“I lost $40,000 in my portfolio.”
“My insurance premium is $3,000 per year.”
“My tax bill is $25,000.”
“My mortgage is $600,000.”
“My portfolio is down 10%.”
Each number needs context.
A $40,000 decline means something different in a $150,000 portfolio versus a $2 million portfolio. A 10% decline may be normal for a long-term portfolio but dangerous for money needed next year. Large numbers should be shown with:
- Percentage
- Time horizon
- Comparison
- Goal impact
- Decision relevance
Instead of saying:
“Your portfolio is down $60,000.”
A better explanation is:
“Your portfolio is down 6.2% year-to-date. For this allocation, that is within the expected range of normal market movement. Because your next three years of withdrawals are covered through cash and conservative assets, this does not currently require selling growth assets.”
Context changes the meaning of numbers.
6. The Generalization Instinct: Avoid Oversimplified Financial Rules
The generalization instinct is the tendency to group things together incorrectly. In financial planning, educated professionals may say:
“All annuities are bad.”
“All debt is bad.”
“All stocks are risky.”
“All bonds are safe.”
“All real estate is a good investment.”
“All insurance is a waste.”
“All taxes should be avoided.”
These generalizations can lead to poor decisions. The truth is more specific. Some annuities are inappropriate, but some may solve an income or longevity problem. Some debt is destructive, but some may be strategic. Some bonds carry risk. Some real estate investments are poor. Some insurance is essential. Good planning requires classification, not generalization. For example:
“Let’s separate speculation from diversified long-term investing.”
“Let’s separate high-interest consumer debt from strategic debt.”
“Let’s separate tax reduction from overall financial improvement.”
Do not let broad labels replace careful analysis.
7. The Destiny Instinct: Your Financial Situation Is Not Fixed
The destiny instinct is the belief that situations are fixed and do not change. In personal finance, people may believe:
“I am just bad with money.”
“I started too late.”
“I will never be able to retire.”
“My spending habits will never change.”
“My family never built wealth.”
These beliefs can become self-fulfilling. Financial planning helps people see that change is possible through small, consistent actions. Progress may come from increasing savings, reducing debt, building emergency reserves, improving investment discipline, completing estate documents, adding insurance protection, improving tax diversification, or creating a retirement income plan. A client’s current situation is not a life sentence. It is a starting point. A useful planning message is:
You are not stuck. You can improve the plan by making one decision at a time.
8. The Single Perspective Instinct: Financial Planning Needs Multiple Lenses
The single perspective instinct is the tendency to rely on one explanation, one tool, or one worldview. This is a major risk in financial advice. Some people see every problem as an investment problem. Others see everything through taxes, insurance, real estate, debt reduction, or estate planning. But real financial planning requires multiple lenses.
A recommendation may be mathematically optimal but emotionally unrealistic. A tax strategy may save money but reduce liquidity. Paying off a mortgage may reduce stress but lower flexibility. A higher equity allocation may improve expected returns but exceed behavioral tolerance. For every major recommendation, evaluate:
- Cash flow impact
- Tax impact
- Investment impact
- Risk management impact
- Estate impact
- Behavioral impact
- Liquidity impact
- Family impact
- Flexibility impact
- Implementation complexity
This is especially important for educated professionals because their financial lives are often complex. Remember, a single lens is not enough.
9. The Blame Instinct: Improve the System, Not Just the Story
The blame instinct is the tendency to look for a clear villain when something goes wrong. In financial planning, people may blame the market, the government, their spouse, their advisor, their employer, the economy, or themselves. Sometimes blame is valid. But blame alone does not improve the plan. A better question is:
What system allowed this mistake to happen?
For example, if a client sold investments during a downturn, the issue may not simply be “the client was emotional.” The system problem may have been:
- No investment policy statement.
- No clear cash reserve.
- Poor risk tolerance assessment.
- Too much portfolio risk.
- No pre-agreed downturn plan.
- Lack of education about volatility.
The goal is not to assign blame. The goal is to improve the system, so the mistake is less likely to happen again.
10. The Urgency Instinct: Be Careful When Something Feels Too Urgent
The urgency instinct makes people feel they must act immediately. This appears in market panic, hot investment opportunities, real estate bidding wars, tax deadline pressure, retirement decisions, emotional spending, business deals, social media investing, political fear, and family pressure. Urgency can be useful in a true emergency. But false urgency is dangerous.
Before acting quickly, ask:
- Is this truly time-sensitive?
- What happens if we wait 24 hours?
- Who benefits from me acting quickly?
- What information is missing?
- Is this decision reversible?
- Is this emotion-driven?
- Does this align with the written plan?
A useful rule is:
Real opportunities can withstand careful review. If a decision cannot survive a thoughtful process, that is a warning sign.
The larger the decision, the more important the process.
Practical Tool 1: The Factfulness Financial Decision Checklist
Before making a major financial decision, ask:
- Am I seeing this as all-or-nothing?
- Am I overreacting to negative news?
- Am I assuming the current trend will continue forever?
- Am I afraid because the risk is real, or because it is vivid?
- Am I looking at the number in proper context?
- Am I overgeneralizing from one example?
- Am I assuming the situation cannot change?
- Am I relying on only one perspective?
- Am I blaming instead of improving the system?
- Am I feeling false urgency?
This checklist is useful before changing a portfolio, retiring, buying a house, selling a business, making a large gift, taking on debt, selling appreciated assets, or reacting to news.
Practical Tool 2: The Reality Check Framework
When a financial concern comes from headlines, anxiety, or uncertainty, use this five-step framework:
Step 1: Name the concern
What specifically are we worried about?
Step 2: Separate fact from interpretation
What do we know for sure? What are we assuming?
Step 3: Measure the impact
How does this affect income, expenses, investments, taxes, insurance, liquidity, or goals?
Step 4: Compare to the plan
Did we already prepare for this scenario?
Step 5: Decide action
Should we act, monitor, or ignore?
Not every concern deserves action. Some concerns deserve monitoring. Some deserve no change.
Practical Tool 3: Factfulness for Retirement Planning
Retirement planning is especially vulnerable to distorted thinking. People may assume:
“I will spend the same amount every year.”
“My health will remain stable.”
“The market return assumption is a promise.”
“If the probability of success is not 100%, I cannot retire.”
“If I retire during a bad market, everything is ruined.”
A factful retirement plan should use ranges, scenarios, and flexibility.
That means:
- Show ranges, not single numbers.
- Clarify which assumptions matter most.
- Separate essential spending from discretionary spending.
- Stress test bad timing.
- Revisit assumptions annually.
- Use context when discussing portfolio declines.
- Prepare emotionally before retirement begins.
Retirement planning is not about pretending we know exactly what will happen. It is about building a plan that can adjust as reality unfolds.
Practical Tool 4: Factfulness for High-Income Professionals
Educated and high-income professionals are often intelligent, busy, analytical, and achievement-oriented. But they still face distorted thinking.
They may have high income, high taxes, equity compensation, real estate exposure, student loans, business ownership, retirement decisions, estate planning needs, and family responsibilities.
For high-income professionals, Factfulness offers several practical lessons:
- Do not confuse income with financial security.
- Do not let lifestyle pressure distort reality.
- Do not let bad news drive investment behavior.
- Do not assume today’s income will continue forever.
- Do not make tax decisions without context.
- Do not generalize from one bad experience.
- Do not assume it is too late to improve.
- Do not rely on only one planning lens.
- Do not blame the market when the system needs improvement.
- Do not act quickly just because something feels urgent.
For educated professionals, the goal is not more information. They already have access to information. The goal is better interpretation.
That is where financial planning becomes valuable.
Final Takeaway
Factfulness teaches us to replace fear, exaggeration, and distorted narratives with context, evidence, and better decision-making. Many financial mistakes do not happen because people lack intelligence. They happen because people misread reality.
They overreact to bad news. They assume trends will continue forever. They fear vivid risks while ignoring quiet long-term risks. They look at numbers without context. They generalize too quickly. They assume their situation is fixed. They rely on one perspective. They blame instead of improving systems. They act with false urgency.
For educated professionals, financial success requires more than income, credentials, and technical knowledge.
- It requires clear thinking.
- It requires separating data from drama.
- It requires distinguishing planning from panic.
- It requires a system for making better decisions under uncertainty.
My one-sentence takeaway from the book is this:
Factfulness teaches us to see reality more clearly so we can make better decisions. In personal finance, better decisions are the foundation of better outcomes.
Note: This article is for educational purposes only and is not individualized financial, tax, legal, or investment advice. Please consult qualified professionals regarding your specific situation.