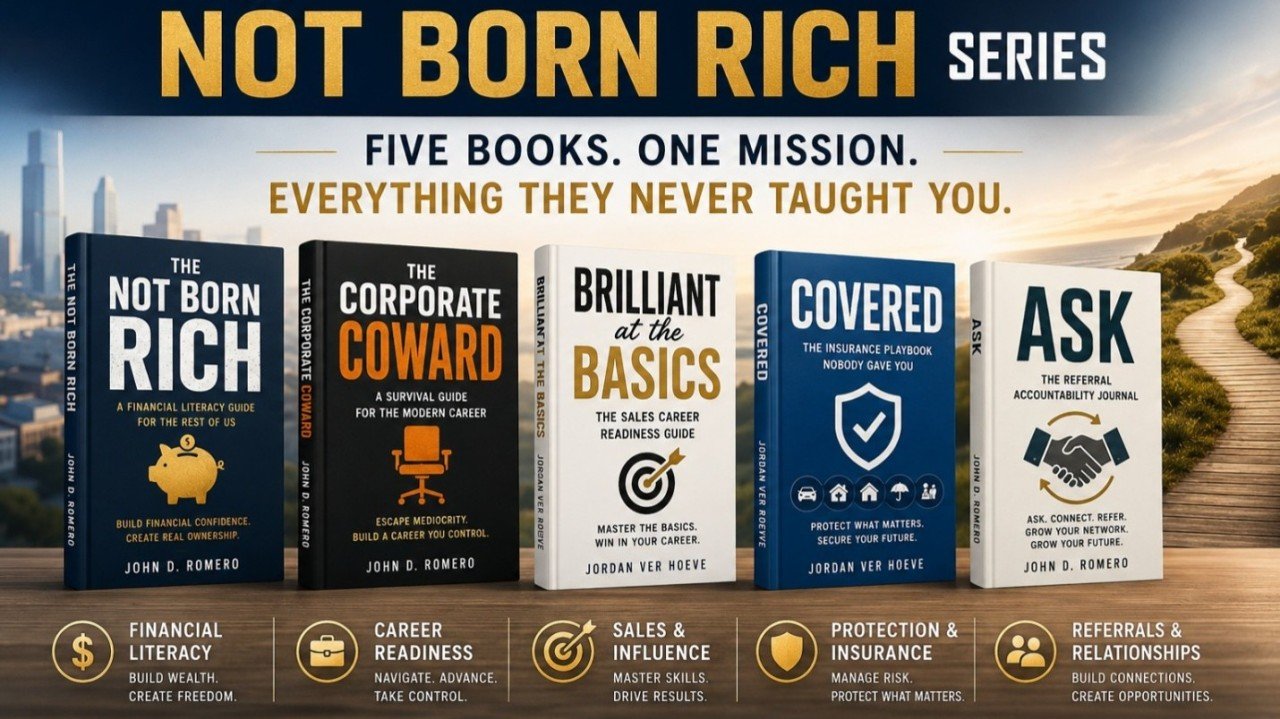
The Not Born Rich series has a simple but powerful message: many people are expected to make major financial and career decisions without ever receiving a real blueprint. The official project describes its mission as helping people build financial confidence and career skills, especially those who “never got a blueprint” for either. The series includes books on financial literacy, career survival, sales and influence skills, insurance, and referral-building. (Not Born Rich)
That message is highly relevant for educated professionals.
Many physicians, engineers, attorneys, professors, executives, dentists, consultants, and business owners are highly trained in their fields. They may have advanced degrees, strong incomes, and impressive credentials. But that does not mean they were taught how to build wealth, protect income, manage taxes, evaluate insurance, negotiate career opportunities, or turn professional success into long-term freedom.
In fact, one of the most dangerous assumptions in personal finance is this:
“Because I am educated, I must be financially educated.”
Those are not the same.
The Hidden Problem: Professional Success Without a Financial Blueprint
Many educated professionals are excellent at earning income but less intentional about converting that income into freedom.
They work hard. They earn well. They pay taxes. They buy homes. They support families. They save something. They invest something. They buy some insurance. They may have retirement accounts.
But often, the pieces are not coordinated.
The result can be a high-income life that still feels financially fragile.
The data supports this concern. The Federal Reserve’s 2024 household well-being report found that only 63% of adults could cover a $400 emergency expense using cash, savings, or a credit card paid off at the next statement, and only 55% had emergency savings sufficient to cover three months of expenses if they lost their primary income source. Even among households earning $100,000 or more, only 75% reported having three months of emergency savings. (Federal Reserve)
High income helps, but it does not automatically create resilience.
Spending also rises with income. The Bureau of Labor Statistics reported that average annual expenditures in 2024 were $78,535 across all consumer units, but $150,342 for the highest income quintile. Housing was the largest spending category at 33.4% of average annual expenditures. (Bureau of Labor Statistics)
This matters because high income can hide financial dependence.
A professional may look successful while still being dependent on one paycheck, one employer, one business, one stock position, one industry, or one lifestyle structure.
That is why financial education for educated professionals must go beyond basic budgeting tips.
It must address the real issues: ownership, protection, taxes, career optionality, insurance, networks, and decision quality.
Lesson 1: Income Is Not the Goal. Ownership Is.
The Not Born Rich platform emphasizes “financial literacy, career readiness, and real ownership.” (Not Born Rich)
That word - ownership - is important.
Educated professionals often focus on income. That makes sense. Income funds the lifestyle and creates opportunity. But income alone is not wealth.
Wealth is built when income is converted into capital.
That capital may include:
- Retirement accounts
- Taxable investment accounts
- Business equity
- Real estate equity
- Intellectual property
- Cash reserves
- Professional reputation
- Referral networks
- Skills that create future income
A physician’s salary is valuable. But salary alone does not create financial independence.
An attorney’s partnership income is powerful. But if all of it is consumed by lifestyle, taxes, and debt, it may not create freedom.
An executive’s stock compensation may build wealth. But if it is concentrated in one company, it may create hidden risk.
A professor may have job stability. But without intentional investing and retirement planning, stability may not become flexibility.
The practical question is:
How much of my income becomes ownership?
Not just consumption. Not just status. Not just temporary comfort. Ownership.
Lesson 2: Career Readiness Is Financial Planning
The series does not only focus on money. It also includes career readiness, corporate survival, sales skills, and referral-building. The official site describes The Corporate Coward as a survival manual for the modern career, Brilliant at the Basics as a sales career readiness guide, and ASK as a referral accountability journal. (Not Born Rich)
This is very relevant to financial planning.
For educated professionals, career capital is often the foundation of wealth.
Your ability to earn, adapt, negotiate, lead, communicate, and build relationships may be more valuable than any single investment early in your career.
Financial planning should therefore include career planning questions:
- Am I too dependent on one employer?
- Are my skills portable?
- Do I have a strong professional network?
- Can I earn income outside my current role?
- Am I building a reputation that creates options?
- Do I know how to negotiate compensation?
- Do I have a referral network?
- Can I consult, teach, advise, speak, write, or serve on boards later?
This matters because many educated professionals do not want traditional retirement. They want flexibility.
They want to work by choice, not necessity.
That requires more than portfolio growth. It requires career optionality.
Lesson 3: Insurance Is Not Boring. It Protects the Plan.
One of the books in the series is Covered: The Insurance Playbook Nobody Gave You, described as covering insurance topics such as car, health, HSAs, FSAs, life, renters, vacation, and jewelry coverage. (Not Born Rich)
This is important because insurance is often ignored by successful professionals.
Many people love talking about investments. Fewer enjoy reviewing disability insurance, umbrella liability, malpractice coverage, life insurance, health insurance, or long-term care exposure.
But protection is part of wealth building.
For high-income professionals, the ability to earn income is often the largest financial asset. A disability, lawsuit, health issue, premature death, or business interruption can damage years of progress.
Insurance is not about fear.
It is about protecting the plan from events that could permanently change the family’s financial life.
Educated professionals should regularly review:
- Disability insurance
- Life insurance
- Umbrella liability coverage
- Professional liability or malpractice coverage
- Health insurance
- Property and casualty coverage
- Business insurance
- Long-term care planning
- Beneficiary designations
The question is not, “Do I have insurance?”
The better question is:
What risks could break my plan, and how are they protected?
Lesson 4: Financial Literacy Must Be Practical, Not Theoretical
The Not Born Rich project describes itself as education, not hype, not get-rich-quick, and not individual financial advice. Its stated purpose is to provide the baseline financial conversation many people were never given. (Not Born Rich)
That is the kind of financial education educated professionals need.
Not slogans.
Not product pitches.
Not market predictions.
Not random tips.
They need practical financial literacy that answers real questions:
- How much should I save?
- How much house can I afford without becoming fragile?
- Should I use Roth or pre-tax retirement accounts?
- How much cash reserve do I need?
- Am I overconcentrated in employer stock?
- Should I pay down debt or invest?
- Do I need disability insurance?
- Am I on track for retirement?
- What tax opportunities should I review before year-end?
- How do I help my children without weakening my own retirement?
- What happens if I lose my job or want to change careers?
- How do I turn income into ownership?
Financial education should not simply make people feel informed.
It should help them make better decisions.
Lesson 5: Educated Professionals Need Systems, Not Just Information
One of the challenges today is that information is everywhere.
But more information does not always create better financial decisions.
Educated professionals already have access to articles, podcasts, spreadsheets, YouTube videos, investment platforms, tax software, AI tools, and financial opinions.
The problem is not lack of information.
The problem is lack of structure.
A useful financial education system should help professionals organize decisions across:
- Income and career
- Cash flow and savings
- Investments
- Taxes
- Insurance
- Retirement
- Estate planning
- Employer benefits
- Education funding
- Behavioral decision-making
- Family responsibilities
- Professional networks and referral capital
This is why comprehensive financial planning matters.
A portfolio alone is not a plan.
A high income alone is not a plan.
A tax strategy alone is not a plan.
A 401(k) contribution alone is not a plan.
A real plan connects all the moving parts.
A Practical Financial Education Checklist for Educated Professionals
Here is a simple checklist inspired by the Not Born Rich message.
1. Turn income into ownership
Ask:
- What percentage of my income becomes long-term capital?
- Am I building investable assets?
- Am I building business, intellectual, or professional capital?
- Am I too focused on income and not enough on ownership?
2. Build a freedom floor
Ask:
- How much monthly spending is essential?
- How long could I live without my current paycheck?
- How much capital would make work a choice, not a necessity?
- What income sources could I build outside my current role?
3. Protect the income engine
Ask:
- What happens if I cannot work?
- Do I have appropriate disability insurance?
- Does my family need life insurance?
- Do I have enough liability protection?
- Are my insurance policies coordinated with my actual risks?
4. Build career optionality
Ask:
- Are my skills portable?
- Do I have a strong network?
- Can I negotiate effectively?
- Can I consult, teach, write, advise, or serve on boards?
- Am I building professional relationships before I need them?
5. Create tax-aware wealth
Ask:
- Am I using retirement accounts effectively?
- Do I have tax diversification: pre-tax, Roth, and taxable?
- Am I managing capital gains?
- Am I coordinating with a CPA?
- Am I making tax decisions before the year is over, or after it is too late?
6. Measure wealth, not lifestyle
Ask:
- What is my net worth?
- What are my investable assets?
- What is my savings rate?
- How much debt do I have?
- What percentage of my wealth is liquid?
- Am I building freedom or just funding appearances?
Why This Message Matters to Me as a Financial Planner and Educator
As a CFP® professional and educator, I believe educated professionals deserve financial education that respects their intelligence but also addresses real life.
They do not need to be talked down to.
They do not need generic advice.
They need clear frameworks, practical tools, and honest conversations.
They need help connecting income, taxes, investments, insurance, estate planning, retirement, employer benefits, career decisions, and family goals.
They need to understand not only what to do, but why it matters.
That is the value of financial education.
It turns complexity into clarity.
It turns income into ownership.
It turns effort into options.
It turns professional success into financial freedom.
Final Takeaway
The Not Born Rich series reminds us that many people were never handed a financial blueprint.
That includes many educated professionals.
Degrees help build careers, but they do not automatically teach personal finance.
Income creates opportunity, but it does not automatically create wealth.
Intelligence helps, but it does not automatically create good financial behavior.
The real goal is to build a system:
Earn well. Save intentionally. Invest consistently. Protect the plan. Manage taxes. Build ownership. Develop career optionality. Use networks wisely. Create freedom.
Financial education is not only for people who are struggling.
It is also for high-achieving professionals who want to convert their success into security, autonomy, generosity, and long-term impact.
Because being “not born rich” does not mean staying financially unprepared.
It means building the blueprint you were never handed.
This article is for educational purposes only and is not individualized financial, tax, legal, insurance, career, or investment advice. Please consult qualified professionals regarding your specific situation.